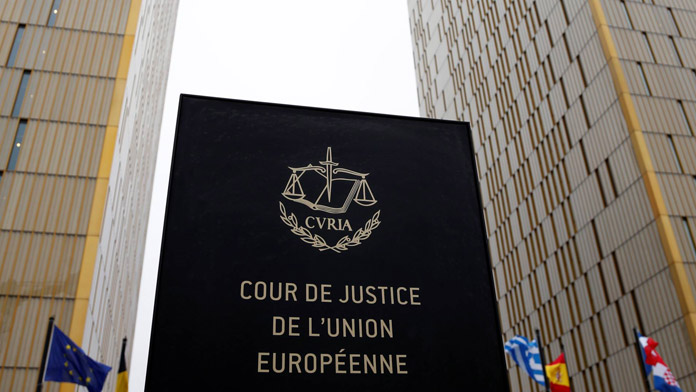
For years, much of the practical response to the anti-abuse clause of the Parent-Subsidiary Directive (“PSD”) has focused on substance: real people, real decisions and a genuine right to the dividends at the EU holding company. On 15 October 2026, in the case Neo Group (C-203/25), the Court of Justice of the European Union (“CJEU”) made clear that substance alone is not enough.
The Court held that Article 1(2) and (3) PSD does not preclude a source State from denying the exemption where the direct parent carries on genuine economic activity, if the distribution forms part of a wider non-genuine arrangement through which the dividends ultimately reach the person controlling the group. The Court did not decide that the arrangement in this case was abusive; that assessment is for the Lithuanian referring body. Genuine economic activity at the direct parent remains relevant, but is not, by itself, sufficient to exclude a finding of abuse.
Facts and ruling
Neo Group UAB (“Neo”), a Lithuanian company was wholly owned by Retal Industries Ltd. (“Retal”), a Cypriot company with genuine activities. In 2016–2017, Neo and a Lithuanian sister company paid Retal around EUR 28.5M in exempt dividends. In 2017, Retal’s Belize shareholder sold Retal to a newly incorporated Cypriot company, Polymer Products Holding Ltd (“PPH”), for EUR 310.4M, payable in 2027; the receivable was assigned to the Cypriot-resident individual controlling both seller and buyer. Retal then distributed about EUR 28.9M to PPH, which passed equivalent amounts to that individual through loans and assignments of receivables, set off against the acquisition debt. The Lithuanian tax authority considered the chain non-genuine and assessed Neo for EUR 2.25M in withholding tax, plus interests and a penalty.
Briefly, the Court’s answers, in four points:
- Genuine activity at the direct parent is relevant but not conclusive. Conduit structures are one example of abuse, not its definition.
- Matching amounts and onward transfers are indications, not proof. Amounts similar to the dividends, even when transferred over time, may point to a non-genuine arrangement, but create no presumption of abuse.
- The arrangement is assessed as a whole. The source State may consider other entities, transactions in other Member States and steps before or after the distribution.
- The subjective element need not be established at the level of the distributing subsidiary. It is sufficient that it is established for at least one participating group company, or for the ultimate beneficiary, who knew or could have known of the arrangement.
Beyond the Danish Cases:
The Danish cases, T Danmark and Y Denmark C116/16 and C117/16, were widely read as a doctrine about conduits. Building on Nordcurrent (C-228/24), Neo Group moves the analysis from the entity to the arrangement. The Court confirms that the direct parent’s status as beneficial owner does not, in itself, prevent the anti-abuse provision; the two assessments are distinct. It also noted that beneficial ownership does not automatically secure treaty relief, and that treaties between Member States cannot override EU law.
The judgment goes further than Advocate General Kokott, who considered that an active beneficial owner should “as a rule” fall outside abuse, and warned that several Member States in a chain could challenge the same flow of profits. The Court left that concern unaddressed, with a risk of double taxation.
The judgment establishes no presumption of abuse against genuine holding companies. The burden of proof remains with the tax authorities, which must demonstrate both that the arrangement, assessed in its entirety, lacks valid commercial reasons reflecting economic reality, and that one of its main purposes is to obtain a tax advantage defeating the object or purpose of the Directive. Since removing withholding tax on intra-EU distributions is precisely what the Directive intends, tax efficiency alone does not establish abuse, nor does the onward distribution of dividends make a structure artificial. When an advantage arising higher up the chain defeats that purpose remains largely unanswered.
Why it matters
The judgment creates no new substance requirement and does not invalidate existing structures; it clarifies how an existing rule applies to arrangements combining genuine companies with non-genuine transactions. As an interpretation of existing EU law, it may also affect historic distributions for periods still open under national procedural rules.
Most exposed are holding structures in Luxembourg, the Netherlands, Cyprus, Ireland or Malta where value is extracted above the holding through acquisition debt, vendor financing or shareholder loans. Exposure varies: outbound dividends from Irish and Luxembourg holdings rely on domestic exemptions rather than the PSD, so pressure falls mainly on dividends paid into them.
Formally, the ruling interprets the PSD alone. Yet it rests on “a general principle of EU law that provisions of EU law cannot be relied on for abusive or fraudulent ends”, which the Danish cases applied to interest and dividends alike. That logic will hardly stay confined to dividends.
In Spain, the judgment is particularly relevant to Article 14.1.h) of the Non-Residents Income Tax Law (“LIRNR”), which governs the withholding tax exemption on dividends paid to EU parents. Its emphasis on the commercial rationale of the wider arrangement may also inform Spanish anti-abuse analysis, including in structures benefiting from the participation exemption under Article 21 of the Corporate Income Tax Law (“LIS”), although that provision is not directly addressed by the judgment.
What should advisers be looking for
7 questions deserve attention:
- Is there a tax advantage that defeats the Directive’s purpose? Whether the ultimate owner would have obtained the same relief directly is a relevant counterfactual, though not necessarily a complete defence.
- Where does the cash go? Dividend-funded debt from share sales, vendor notes or deferred consideration reflects the Neo Group pattern.
- Do amounts mirror the dividends? Ordinary cash pooling and regular repatriation are not inherently suspicious; matching flows require examination, not a conclusion of abuse.
- Does the holding company decide? The board should consider and minute how dividends are used.
- Does the original rationale still exist? An arrangement may become non-genuine if maintained after its commercial reasons cease.
- Who bears the risk? The distributing subsidiary; in Mergers & Acquisitions address it through due diligence and indemnities.
- Is the file up to date? Memoranda and rulings focused on recipient-level substance should cover the whole chain.
Conclusion
Neo Group is a judgment of balance, but it leaves the hardest question open: when does a tax advantage defeat the object or purpose of the PSD? Removing withholding tax on intra-EU dividends is the very benefit the Directive confers, so applying the exemption, or enjoying a lower tax burden, cannot, in itself, establish abuse. Nor does the Court explain when an advantage arising elsewhere in the chain is connected closely enough to the Directive to justify denying relief at source. The judgment does not condemn every advantage obtained higher up the chain, or every tax-efficient use of PSD dividends.
Substance at the direct parent no longer closes the enquiry, yet artificial elements elsewhere do not, on their own, establish abuse. Future cases must say how far up the chain, and how far back in time, the review may reach, and how overlapping challenges by several Member States are to be avoided. Until then, substance remains relevant, but it is no longer a shield.
The opinion expressed in this article is exclusively that of the author and does not reflect and cannot be related to her professional environment.